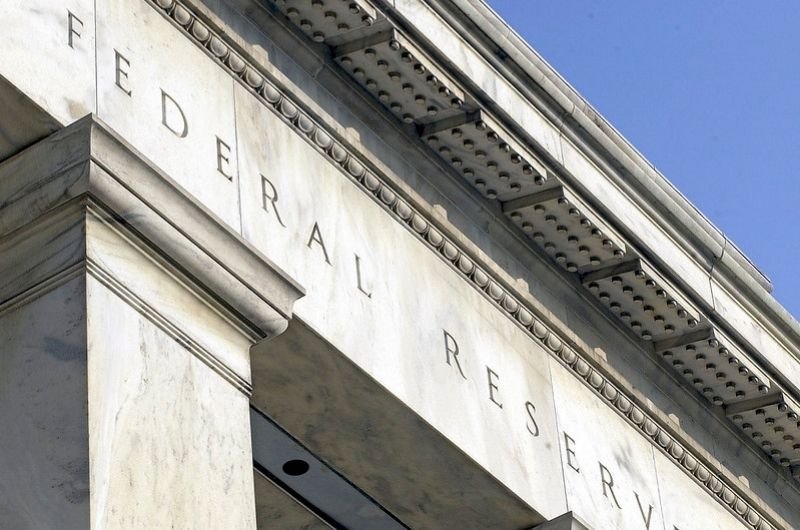
Americans could soon face another increase in borrowing costs as the Federal Reserve prepares for a closely watched interest-rate decision Wednesday, with economists increasingly expecting policymakers to raise rates for the first time in more than three years.
The Fed is widely expected to consider a quarter-percentage-point increase following stronger inflation readings and renewed pressure from rising energy prices. A Reuters poll released Monday found 85% of economists expect a hike, which would lift the federal funds target range from its current 3.50%–3.75% to 3.75%–4.00%.
For consumers, a Fed increase can eventually make several types of borrowing more expensive. Credit cards carrying variable rates can respond relatively quickly, while rates on some home-equity lines and other variable-rate loans may also rise. Auto and personal-loan rates are not directly set by the Fed, but a higher-rate environment can make new financing more expensive.
Mortgage rates work differently because they are influenced heavily by longer-term bond yields rather than moving directly with the federal funds rate. But those yields have also been climbing: the benchmark 10-year Treasury yield approached 5% Monday, its highest level in nearly three years. That could keep pressure on mortgage rates and housing affordability even beyond Wednesday’s Fed decision.
There can be a small upside for savers. Banks may offer higher yields on savings accounts, money-market accounts and certificates of deposit when interest rates rise, although institutions decide individually how much of an increase to pass along to customers.
The Readovia Lens
Wednesday’s decision could reach far beyond financial markets. For households already dealing with higher prices, another rate increase could make carrying credit-card balances and taking out new loans more expensive, making the Fed’s next move something consumers may feel directly in their monthly budgets.